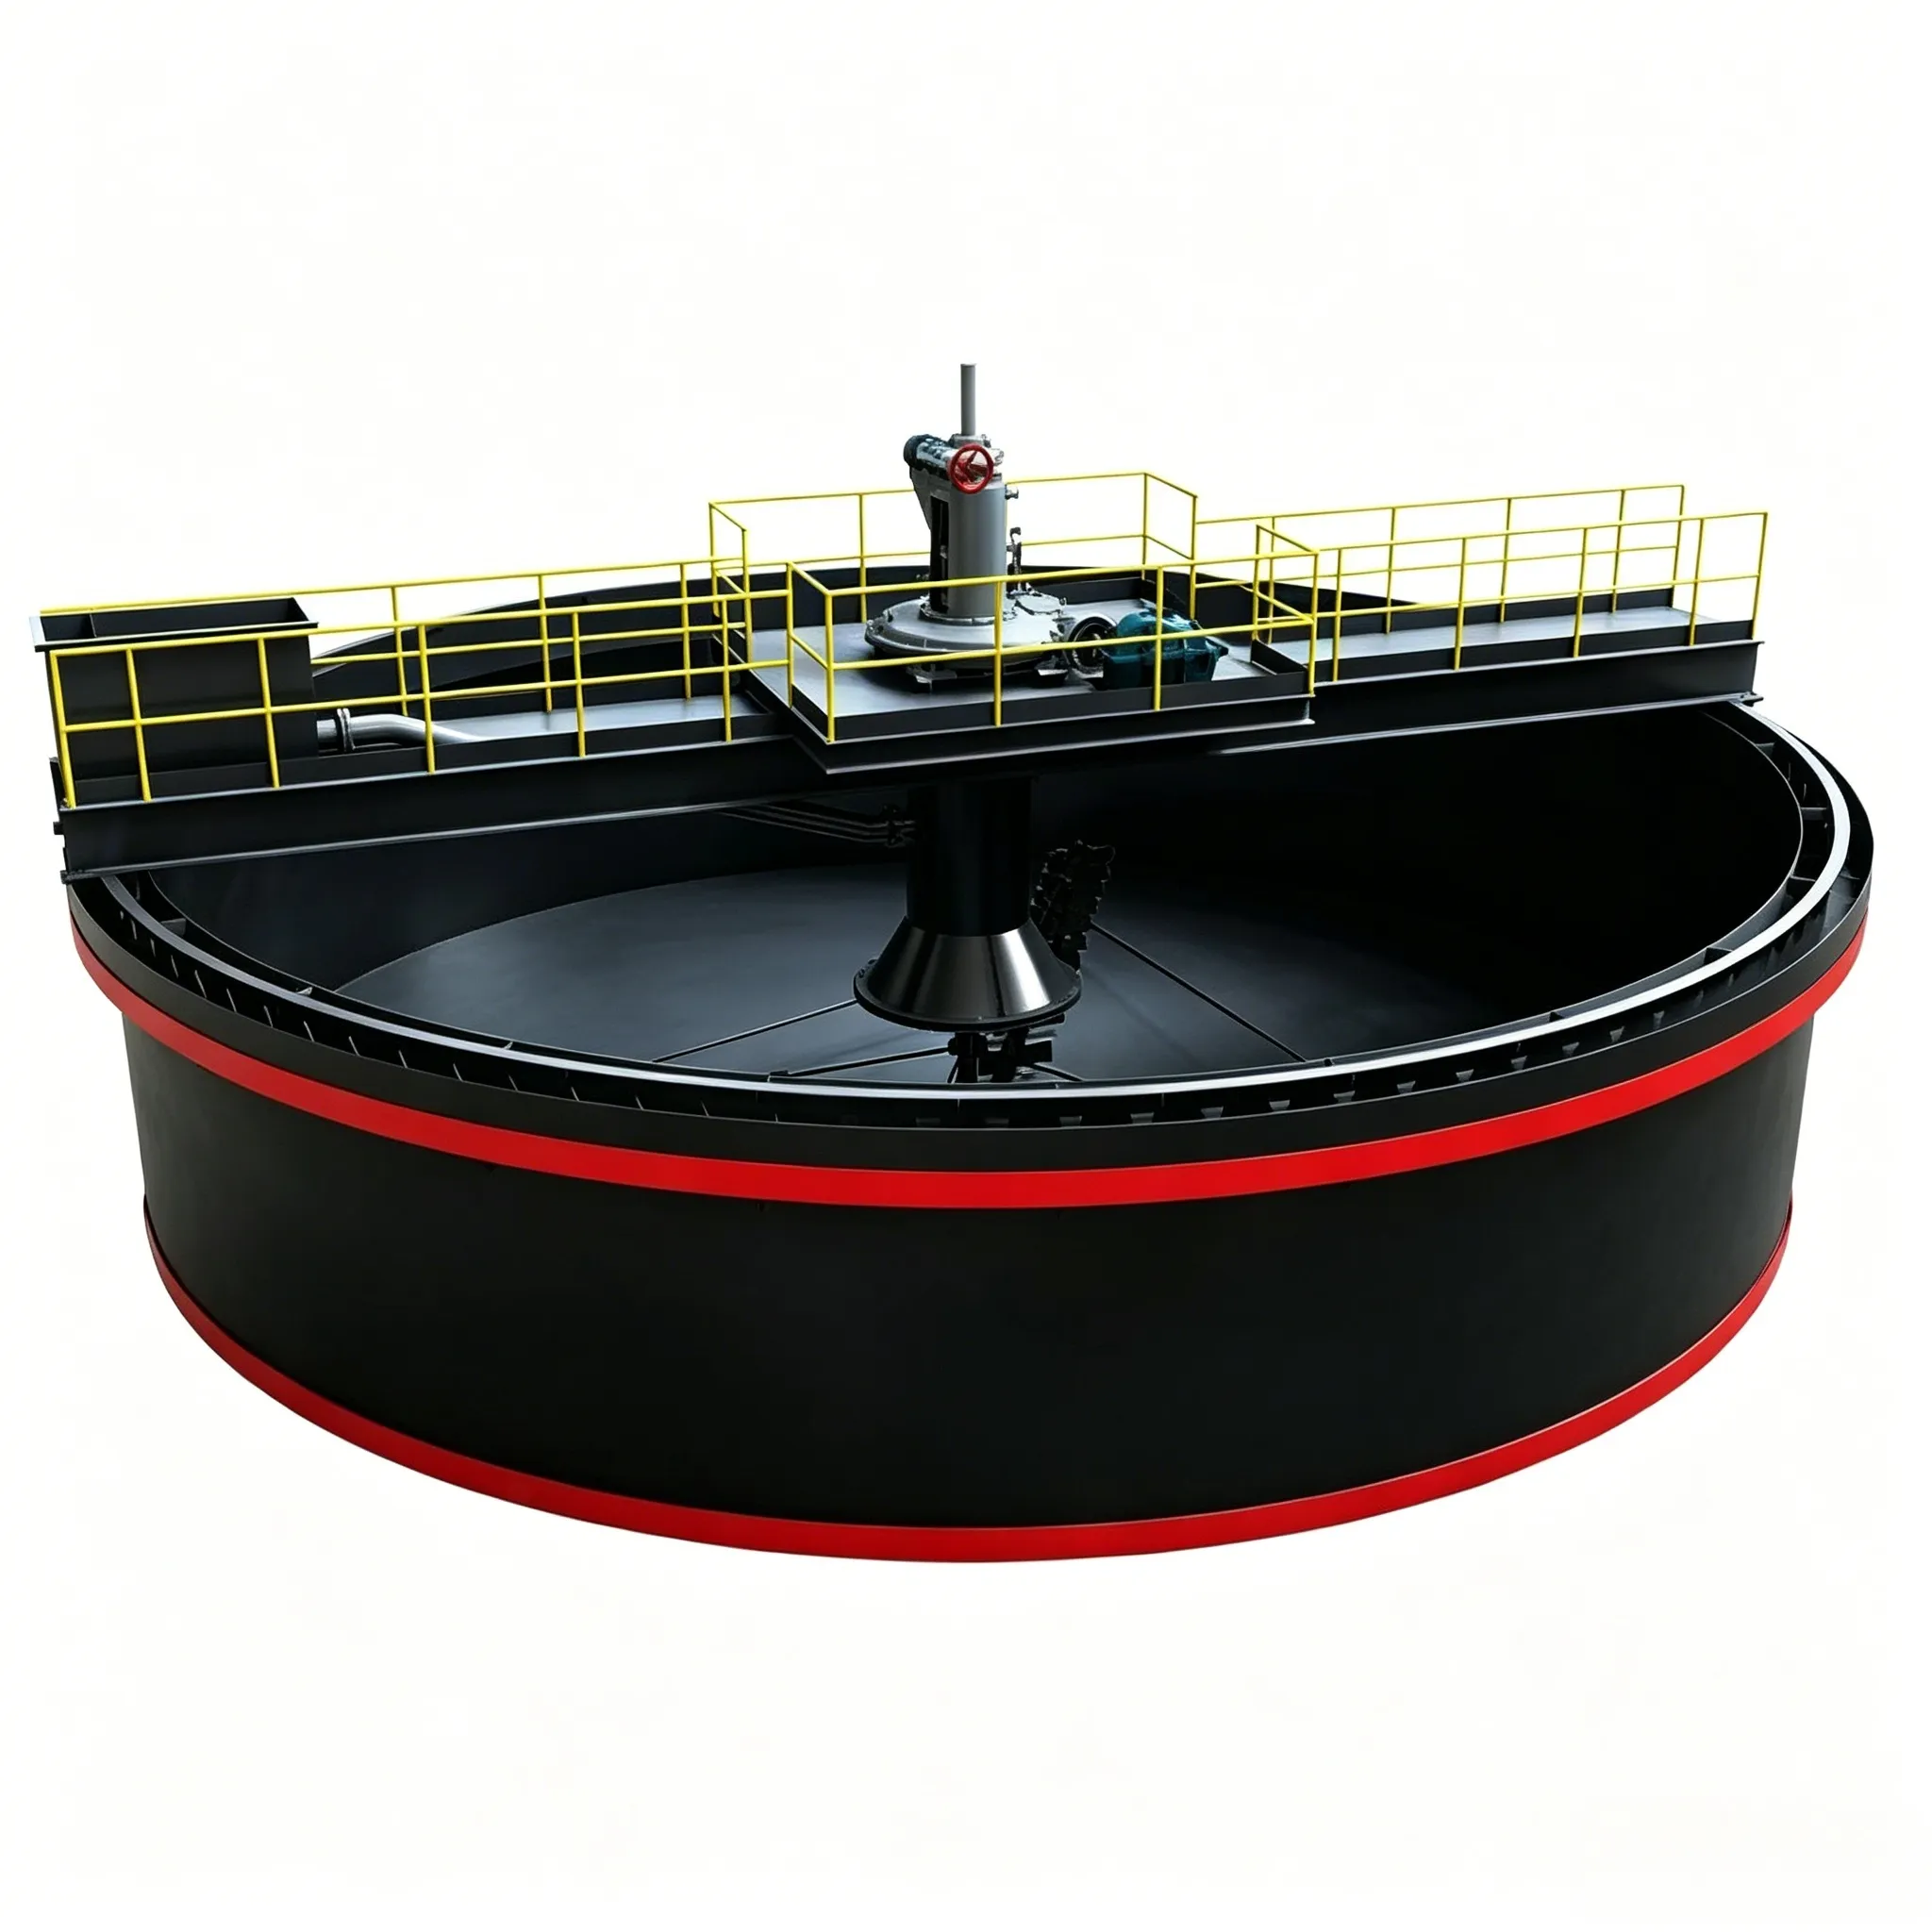
Addensatore ad alta efficienza
Addensatore ad alta efficienza L'addensatore ad alta efficienza è un nuovo tipo di impianto di addensamento…

I. Transaction parties and overview
Acquirer: Norin Mining (Hong Kong) Limited, under China North Industries Group’s Norin Mining, with overseas copper-cobalt mine development experience (Kamoto and Pumpi projects in the DRC)
Seller: London AIM-listed Asiamet Resources Limited
Target: acquisition of 100% equity of Indokal Limited; Indokal holds, through Indonesian local company PT KSK, 100% interest in the KSK (Kalimantan Surya Kencana) Contract of Work (CoW), with the core asset being the BKM copper project (Beruang Kanan Main), along with the BKZ polymetallic deposit and multiple exploration targets Transaction consideration: US$105 million cash, cash & debt free Signing date: 2025-11-06, Asiamet announcement
Timeline
II. Project resources (JORC standard, BKM main orebody)
BKM is a volcanogenic massive sulphide (VHMS) copper deposit, suitable for open-pit heap leaching SX-EW hydrometallurgical production of cathode copper.
As of the 2021 JORC resource report (0.2% Cu cut-off grade)
Total resources: 69.6 Mt @0.6% Cu, 451.9 kt copper metal
Measured: 20.6 Mt @0.7% Cu, 148.5 kt Cu
Indicated: 34.1 Mt @0.6% Cu, 212.6 kt Cu
Inferred: 15.0 Mt @0.6% Cu, 90.8 kt Cu
Proven + Probable reserves: 51.5 Mt @0.6% Cu, 303 kt copper metal
Proven: 21.1 Mt @0.6% Cu, 137 kt Cu
Probable: 30.4 Mt @0.5% Cu, 166 kt Cu
BKZ polymetallic orebody (about 800 m north of BKM, inferred resources)
Upper Polymetallic Zone (zinc-lead-silver-gold)
High-grade domain: 750,000 t, Zn 8.0%, Pb 3.4%, Ag 50 g/t, Au 0.35 g/t
Low-grade domain: 590,000 t, Zn 1.6%, Pb 0.5%, Ag 13 g/t, Au 0.15 g/t Lower Copper Zone (copper-silver)
1.1 Mt @1.1% Cu, Ag 13 g/t The KSK mining area also has multiple copper-gold targets such as BKS and BKW, with further resource extension potential; it is a platform-type asset, and the Phase 1 BKM is only the starting development.
III. Phase 1 BKM development plan (May 2025 optimized feasibility study OFS)
Process route: open-pit mining + heap leaching + SX-EW, directly producing LME Grade A cathode copper
Design capacity: 10,000 tonnes of cathode copper per year
Initial mine life: 12.8 years, full-life copper production 124,022 tonnes of cathode copper
Stripping ratio: 0.77:1 (very low, good open-pit economics)
Average soluble copper grade: 0.55%, heap leach recovery 79%
Economic indicators (base copper price US$4.30/lb, discount rate 8%, after tax)
Total initial capital expenditure: US$178.4 million (including contingency)
C1 cash cost: US$1.79/lb Cu; AISC all-in sustaining cost: US$2.37/lb Cu
After-tax NPV₈: US$122.4 million; IRR: 17.7%; static payback period: 4.5 years
Full-life mine revenue: US$1.192 billion, EBITDA: US$612.2 million (excluding closure rehabilitation costs)
Indonesian tax regime: tax incentives may be available, 7 years of full corporate income tax exemption + 50% reduction for the following 2 years; copper product royalty 7%
Phased expansion plan (Norin Mining may optionally proceed with subsequent development after closing)
Phase 1: current feasibility-study heap leach project, processing oxide/soluble copper ore
Phase 1A: expand heap leach scale
Phase 2: process BKM primary sulphide copper resources (in-situ sulphide copper about 245 kt Cu) + residual copper in heap leach waste (about 80 kt Cu)
Phase 3: develop the BKZ zinc-lead-silver-copper polymetallic orebody, adding cash flow from multiple metal products
IV. Project highlights and risks
✅ Advantages





 English English
 Spanish
 Russian
 Arabic
 Swahili
 French
 Turkish
 Portuguese
 Korean
 Japanese
 German
 Italian